

Digital banking in 2026 is entering a new phase. Mobile access, instant transactions and digital self-service are increasingly baseline expectations, while AI, personalization, open ecosystems and automation are changing how financial services behave around the customer. The competitive question is therefore shifting from “Is the bank digital?” to “What kind of digital relationship can the bank create?”
AI is accelerating the transition. It can adapt interfaces, interpret financial context, automate routine actions, provide conversational guidance and increasingly act on customer goals. But technology alone does not create a differentiated banking experience. When every financial institution gains access to similar AI models, APIs and infrastructure, the strategic advantage comes from how those capabilities are translated into customer value, trust and distinctive product behavior.
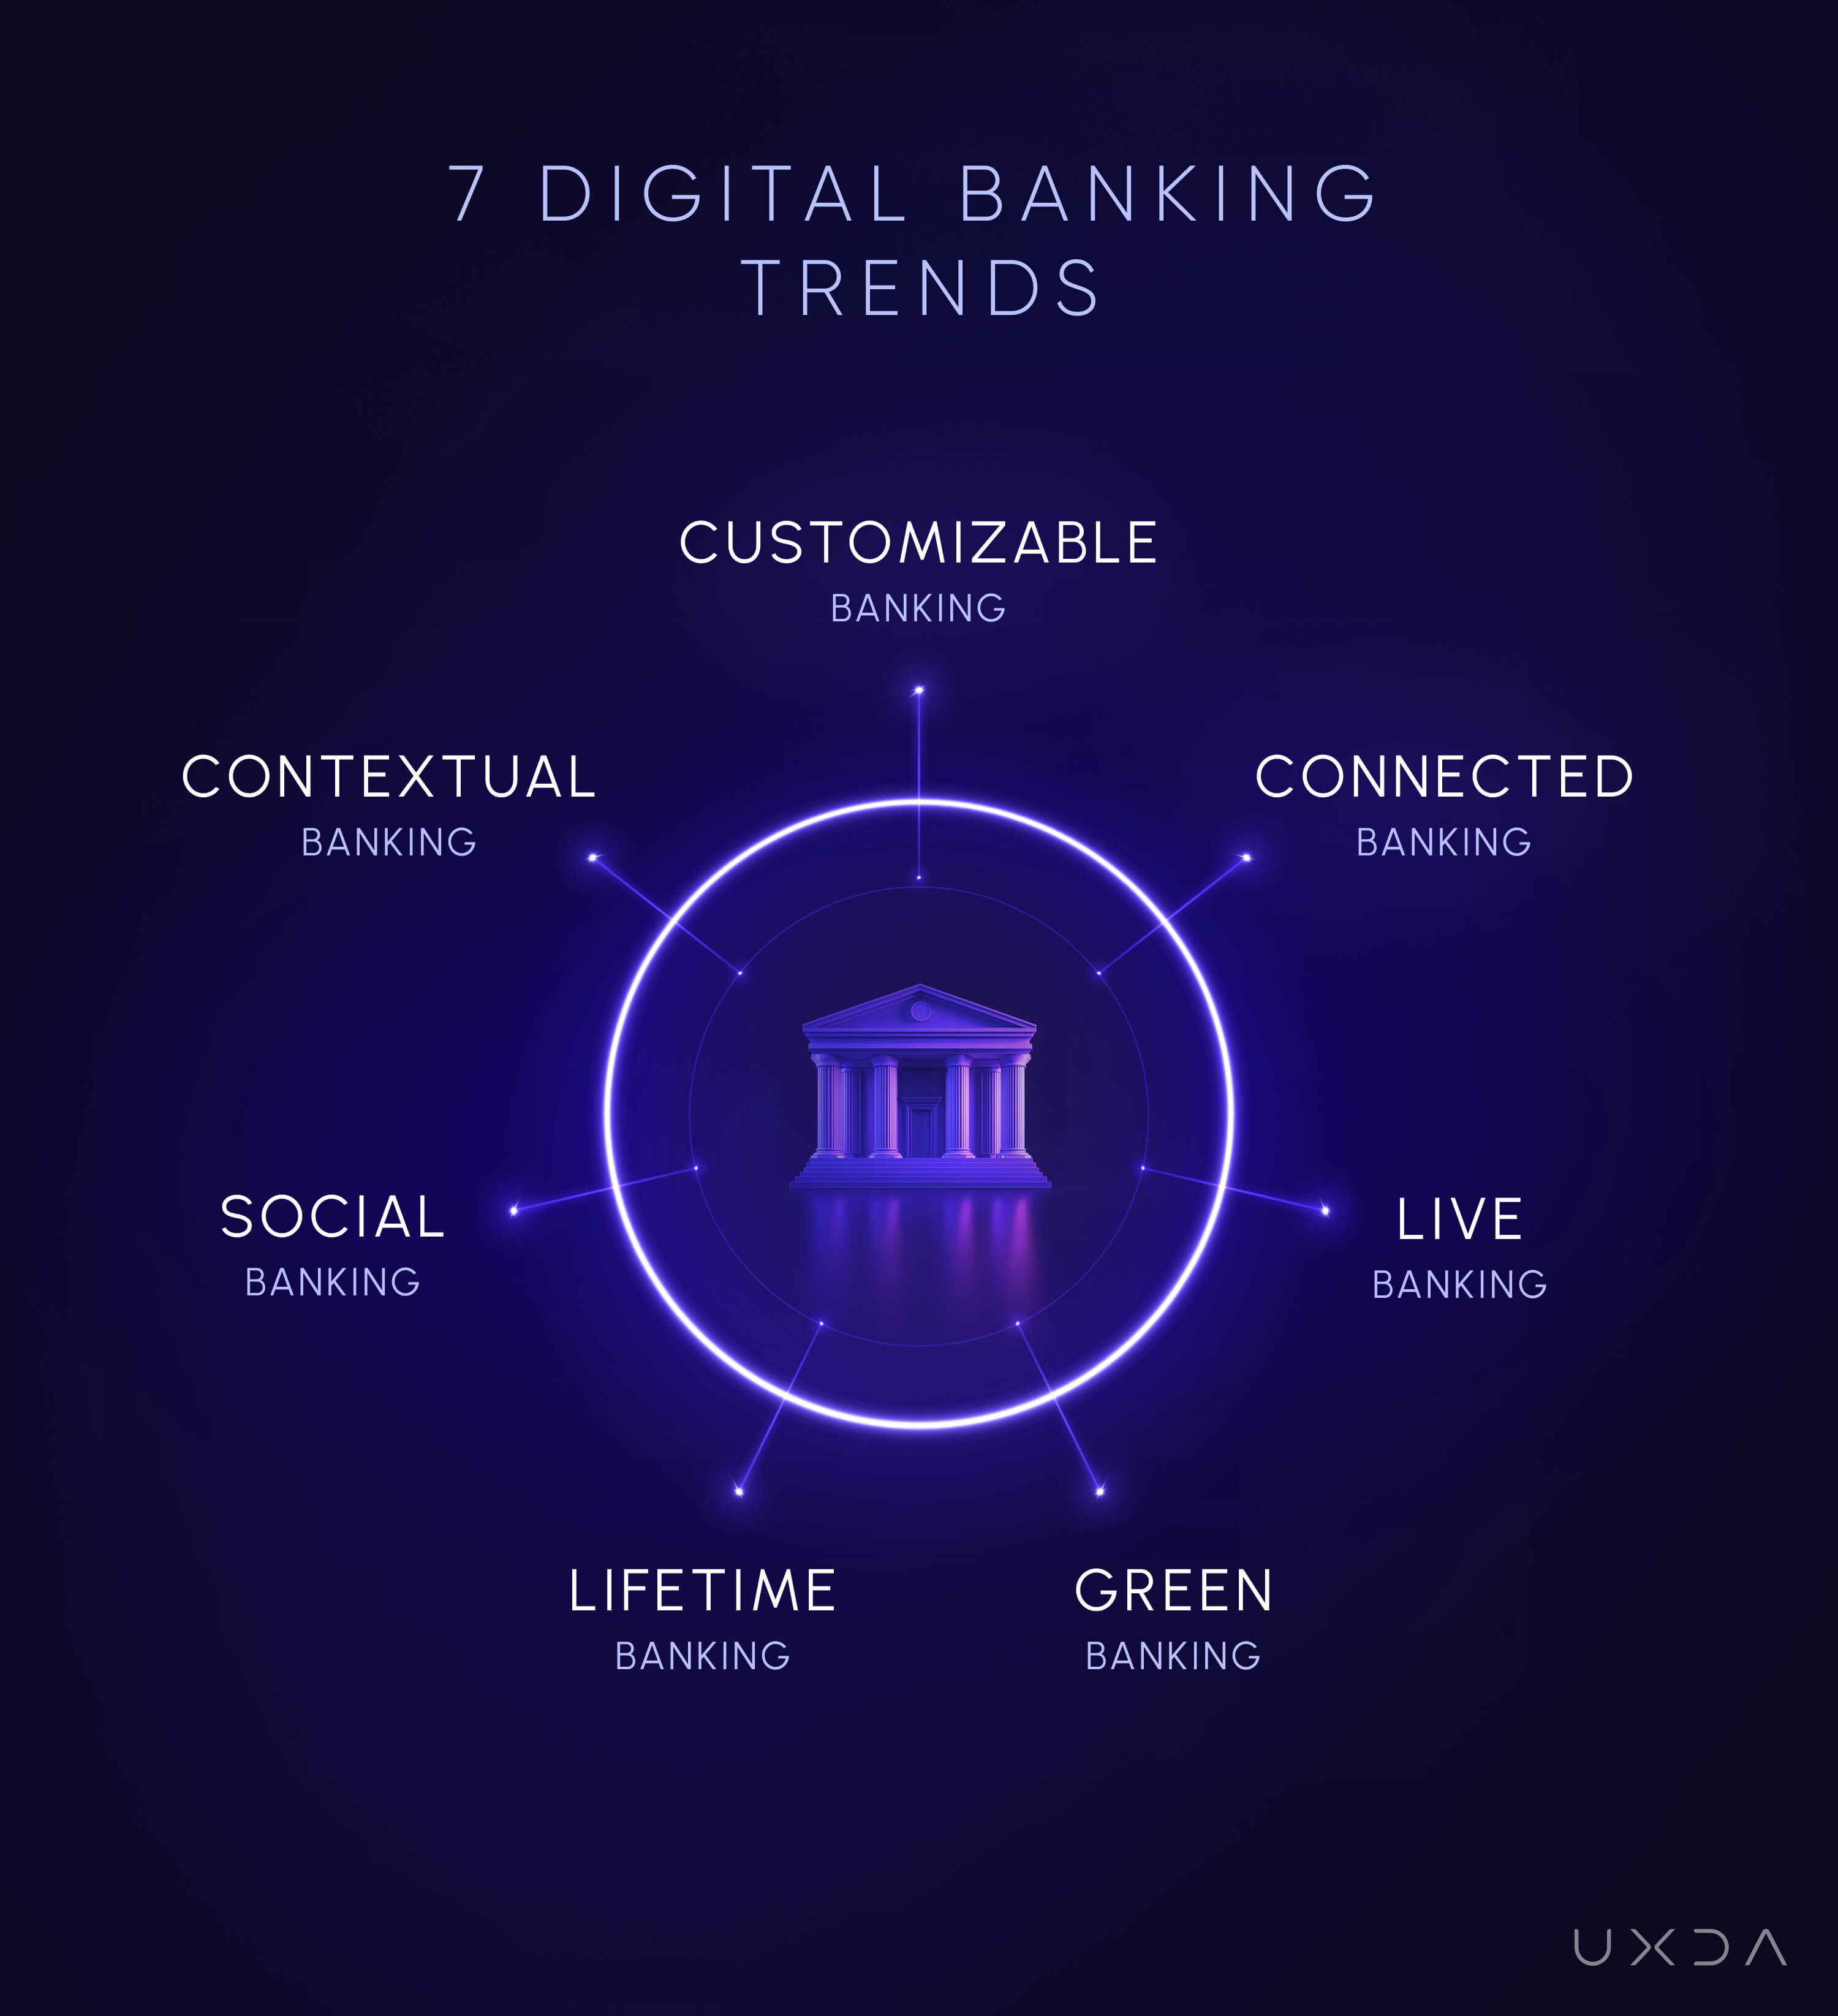
From a customer experience perspective, seven digital banking trends illustrate this transition particularly well: Customizable, Connected, Live, Contextual, Green, Social and Lifetime Banking.
Together, they point toward a wider transformation—from standardized banking products toward more adaptive, connected and intelligent financial experiences.
What Are the Most Important Digital Banking Trends in 2026?
Digital banking in 2026 is being reshaped by AI and agentic systems, hyper-personalization, embedded finance, open ecosystems, intelligent automation, real-time data and increasingly adaptive customer experiences.
But these technologies are only one side of the transformation.
From a customer experience perspective, the more important question is what kind of banking experience these technologies enable. AI, APIs, automation, data and digital identity provide the infrastructure. The visible transformation happens when banking becomes more customizable, connected, conversational, contextual, responsible and integrated into customers’ financial lives.
UXDA identifies seven experience-level digital banking trends emerging from these technological shifts:
- Customizable Banking — adaptive experiences shaped around individual needs.
- Connected Banking — continuity across channels, products and ecosystems.
- Live Banking — intelligent digital assistance combined with human expertise.
- Contextual Banking — relevant guidance and next-best actions based on customer context.
- Green Banking — sustainable financial choices translated into understandable digital experiences.
- Social Banking — participation, peer insight and customer co-creation.
- Lifetime Banking — financial guidance that evolves with customers across life stages.
Together, these trends represent a broader shift from banking as a collection of transactions toward banking as an intelligent, adaptive and continuously evolving financial relationship.
Every Digital Banking Trend in 2026 is Powered by AI
AI is not absent from these seven trends—it is increasingly the intelligence layer behind all of them. AI is an invisible engine powering all of the critical transformations in digital banking today. AI-driven analytics, personalization and automation serve as the underlying technology enabling each trend that we explore in this article.
- AI → adaptive customization;
- AI → contextual personalization;
- AI → conversational/live banking;
- AI → proactive lifetime guidance;
- AI → automation/invisible banking.
By providing the intelligence that refines customer interactions, notifications and advisories; optimizes service delivery; and even supports ESG-driven banking, AI catalyzes every dimension of banking innovation. Rather than existing as a separate phenomenon, AI’s presence ensures that current banking trends achieve the adaptability, responsiveness and meaningful impact that customers increasingly demand.
Next-gen ultimate banking trends challenge the status quo, requiring financial brands to step forward as true lifestyle partners, empathetic advisors and community builders. By embracing these financial services trends, banks can elevate their brand from a background utility to a meaningful presence that customers trust, admire and recommend.
The time for incremental tweaks is over. It’s time to be bold, to provoke change from within and to embrace a future that rewards innovative thinking and courageous action.
1. Customizable Banking: AI-Personalized and Adaptive Banking UX
What Is Customizable Banking?
Customizable Banking is a digital banking model that adapts the interface, information and functionality around individual customer needs and preferences. It can include configurable dashboards, personalized shortcuts, adjustable information density and AI-driven experiences that help customers prioritize the financial tools and insights most relevant to them.
Empowering Brand Personalization
Customizable Banking signals a radical departure from off-the-shelf white-label interfaces and rigid product bundles. Instead, it gives customers the power to remix and reconfigure their entire banking environment. Customizable Banking directly challenges the antiquated notion that one-size-fits-all solutions are acceptable. Banks that will not allow this level of customization face the risk of pushing away customers who will expect digital experiences to be as precisely tailored as their social media feeds.

Garanti BBVA Securities UX case study
Customizable Banking invites customers to build their own bespoke financial experiences. This shift turns financial brands into an open canvas—a dynamic ecosystem in which users shape their own experiences. Each widget they add, remove or rearrange becomes a brushstroke in their personal brand journey. Rather than enduring a cookie-cutter set of tools, users pick and choose features and layouts that reflect their personal needs, goals and lifestyles.
Instead of limiting financial services to native features, a Customizable Banking super-app approach unites multiple in-house and third-party services through open APIs. This wide-ranging marketplace of tools—from budgeting and investment platforms to insurance products and tax solutions—lets customers easily select, combine and configure components based on their unique needs. The result is a fluid, dynamic environment that evolves as user preferences and financial complexity grow over time.
Behind the Customizable Banking Trend
Modern consumers increasingly demand control and uniqueness in their digital lives. They are tired of platforms that waste screen space on irrelevant features and yearn for experiences that feel made just for them.
- Customers increasingly encounter configurable digital experiences across productivity, media and commerce, raising expectations for greater control over relevance and information density in financial services.
- Challenger banks and Fintech startups have shown that niche, modular offerings win customers who crave specialized tools. Established banks must keep pace or risk appearing rigid.
- APIs, microservices and widget-based frameworks enable financial brands to offer plug-and-play components that users can rearrange at will.
Impact on Your Financial Brand
When customers actively customize their financial toolkit, they feel invested in your brand, seeing it as a platform that reflects their individuality. Such personalization creates emotional affinity and a narrative of self-expression. By enabling customers to define their own experience, your financial brand moves from mass-market sameness to a uniquely co-created brand identity, reinforcing that you respect and celebrate each customer’s personal story.
By harnessing a Customizable Bank super-app approach, banks give customers the freedom to mix and match modules that perfectly align with their lives and goals. This reduces frustration and fosters a sense of ownership, as users curate services that resonate with their financial journeys. Over time, customers experience a dynamic, evolving platform that deepens engagement, extends retention and nurtures higher satisfaction and trust in their banking relationship.
Instead of dealing with clunky interfaces and irrelevant features, customers pick and choose only the components they need. This flexibility reduces friction, encourages frequent engagement and creates a sense of personal ownership that establishes long-term loyalty.
Use Case Examples
- Customizable Interfaces: A new graduate might opt for simple modules focused on expense tracking and basic savings, while a small business owner might integrate accounting software, payroll services and specialized analytic tools directly within their banking dashboard.
- Ecosystem Expansion: With open APIs, customers can seamlessly add niche third-party providers, such as ethical investment advisors or real-time crypto trading platforms, expanding their financial management capabilities without leaving the bank’s ecosystem.
- Adaptive Complexity: As customers’ financial literacy and ambitions evolve, they can easily incorporate more advanced features—like advanced tax planning or AI-driven portfolio optimization—into their personalized setup.
2. Connected Banking: Omnichannel and Embedded Financial Experiences
What Is Connected Banking?
Connected Banking creates a continuous financial experience across products, channels and external ecosystems. It allows customers to move between mobile banking, online banking, human support and partner services without losing context, repeating information or navigating disconnected versions of the same institution.
Truly Seamless Experiences
Why force customers to juggle passwords, repeat their stories and navigate clunky silos? Banks that remain stuck in patchwork approaches are signaling that they value their own operational comfort over their customers’ time and sanity.

Connected Banking ensures that customers’ banking journeys are consistent and fluid across channels—mobile apps, desktops, voice assistants, wearables and even partner ecosystems. Instead of logging in repeatedly or restarting conversations, customers glide seamlessly, enjoying a coherent brand personality everywhere.
Think of it as giving your brand a single, coherent voice that customers hear everywhere they go. Instead of fragmented touchpoints speaking in dissonant tones, your unified brand presence stays consistent and comforting across the entire digital landscape.
Banks leverage cryptographic credentials, biometric security and encrypted data-sharing networks to ensure safety and transparency. An integrated super-app might unify multiple banking functionalities and even third-party services, enabling customers to manage finances, access advice and complete transactions anywhere, anytime.
Behind the Connected Banking Trend
Today’s digital natives expect brand interactions to feel continuous, like a well-orchestrated narrative. A good example is Apple's interconnected ecosystem, which extends the customer experience beyond interactions with separate products. Fractured experiences undermine trust and brand perception.
- Consumers now multitask across devices and platforms. They expect their financial brand to remember their preferences and context, just like streaming services remember their watch lists.
- Big tech players and super-apps have raised the bar by unifying shopping, communication and entertainment in single ecosystems—customers demand banks to respond in kind.
- Advances in biometrics, cryptographic authentication and secure data-sharing protocols allow seamless identity verification, making cross-channel consistency not just possible but secure and friction-free.
Impact on Your Financial Brand
When your brand presence feels continuous—regardless of the channel—it symbolizes reliability, thoughtfulness and technical sophistication. Customers no longer struggle with clumsy logins or repetitive requests; instead, they feel guided by a singular brand personality that remembers them. This cements a perception of your brand as an orchestral conductor, elegantly harmonizing every encounter into a smooth, signature experience.
Customers float effortlessly among channels and interfaces without repetitive steps. The unified view of personal information reduces friction and cognitive load, leaving customers feeling known, understood and secure. This consistency builds trust, streamlines decision-making and underscores the bank’s commitment to a cohesive, user-centric relationship.
Connected Banking’s synchronized data and secure biometric authentication reduce wait times and cognitive load. The result is a consistent user-centric experience.
Use Case Examples
- Omni-Channel Consistency: A customer begins a loan application on a smartphone app, continues it on a website and finalizes details via a voice assistant—all without the need to re-enter personal information.
- Contextual Handoff: A banking consultant can pick up a conversation exactly where an AI advisor left off, ensuring continuity and no repeated queries.
- Embedded Banking: Banks partner with retailers, wellness apps or ride-sharing platforms so that customers can pay, save or invest seamlessly within other everyday digital services.
3. Live Banking: Conversational Banking AI With Human Expertise
What Is Live Banking?
Live Banking combines intelligent digital assistance with seamless access to human expertise when customers need additional guidance. AI can handle routine questions and interactions efficiently, while more complex, sensitive or consequential situations can transition to a human advisor without forcing the customer to restart the journey.
Humanizing Financial Brands
By insisting that human empathy should remain central, Live Banking stands for technology that enhances humanity without replacing it. It merges the algorithmic sharpness of AI with empathetic human counsel, adding a warm, human heartbeat to digital interactions.

Live Banking fuses AI-driven responsiveness with empathetic human insights to make digital banking feel alive and attentive. It’s a conversation, not a transaction. Customers can quickly resolve routine issues with AI or seamlessly escalate to human advisors who understand their emotional and financial contexts.
Conversations flow naturally, powered by advanced natural language processing and proactive AI diagnostics. Customers can receive on-demand consultations or periodic financial check-ups aligned with their context and lifestyle.
Instead of a static, mechanical presence, your brand could create a digital persona that will feel alive, responsive and genuinely caring—like a knowledgeable friend who can read the room, not just a chatbot churning out scripted lines.
Behind the Live Banking Trend
As digital ecosystems expand, customers yearn for human warmth and understanding. Function-driven automation can feel soulless. Blending technology with the human touch should meet emotional needs, build trust and enhance perceived brand humanity through customer-centered experience.
- Digital banking is no longer a novelty. It’s the norm. Now customers want deeper guidance, reassurance and empathy, especially for complex financial services.
- Competition is no longer just about low fees or fancy features. Institutions gain an edge by offering humanized, emotionally intelligent services that will stand out in a sea of bots.
- Natural language processing, sentiment analysis and video chat integrations make it easier to deploy “humane” AI assistants and smooth human-to-bot transitions.
Impact on Your Financial Brand
By weaving emotion-driven experience into digital channels, your brand transcends the cold, transactional perception often associated with financial services. Customers feel heard, valued and respected, so they can enjoy the service. This emotional resonance creates a halo effect that elevates brand perception, making your institution feel like a caring advisor rather than a faceless vendor. In a market full of sterile interfaces, a humanized digital brand will stand out as both dependable and soulfully engaged.
As digital interactions become more personal and responsive, customers feel genuinely cared for. The immediacy and warmth of human-like engagement reduces stress and confusion, while timely guidance encourages healthy financial behaviors. This supportive, humanized layer builds lasting trust, making customers feel comfortable and confident in their banking relationship.
Use Case Examples
- Conversational Query Resolution: An AI assistant rapidly handles balance inquiries, transaction categorization or simple troubleshooting, escalating to a human advisor for more complex and nuanced financial advice.
- Periodic Financial Health Reviews: Scheduled sessions—like a virtual financial wellness check—help customers understand their credit score, investment performance and savings plans.
- Adaptive Support: If AI detects emotional distress or confusion, it seamlessly brings in a human advisor who reassures, clarifies complex products or helps navigate major decisions.
4. Contextual Banking: Hyper-Personalization of Banking and Next-Best Action
What Is Contextual Banking?
Contextual Banking adapts financial guidance, services and interactions to the customer’s current situation, behavior, goals and journey. Instead of relying only on static personalization or generic product offers, it uses relevant data and real-time context to determine the most useful next action—which may be guidance, a warning, a service, an offer or no intervention at all.
Tailored Advice, Perfect Timing
Banks that fail to personalize their services risk becoming that annoying acquaintance who never listens and keeps pushing irrelevant solutions. By refusing to read the room, they admit they care more about pushing products than enhancing lives.

Contextual Banking uses behavioral data, life events and user-defined preferences to offer well-timed, genuinely helpful guidance. Instead of blanketing customers with random product pitches and pushing impersonal promotions, a financial brand’s messaging arrives as a thoughtful recommendation at the right moment—aligning perfectly with a customer’s situations, moods and goals.
Contextual Banking relies on predictive analytics and AI to suggest further steps, offer relevant products or provide timely alerts aligned with each customer’s situation—whether it’s a life milestone, a recent job change or subtle shifts in spending patterns. Your brand no longer pushes generic offers; it “whispers” timely guidance.
Customers control their data and communication styles, allowing them to request proactive alerts or context-sensitive recommendations that complement their emotional and practical needs.
Behind the Contextual Banking Trend
With hyper-personalized recommendations becoming the norm in entertainment, shopping and content, banking must offer the same level of intuitive relevance. Customers now expect brands to understand their context and deliver meaningful suggestions instead of intrusive support.
- Consumers reject one-size-fits-all marketing and gravitate instead toward brands that anticipate their needs and serve them proactively.
- Fintechs use machine learning to analyze user data and behavioral patterns, setting a new standard for “just-in-time” guidance that big banks must match.
- AI-driven recommendation engines, event-triggered communications and integrated data streams make real-time contextualization both feasible and scalable.
Impact on Your Financial Brand
This shift from generic marketing to bespoke, situation-aware assistance firmly positions your brand as a reliable ally. The brand’s voice shifts from a sales pitch to a wise, considerate companion who “gets” its customers. Over time, this relevance fosters deep trust, reinforcing a brand image built on respect and meaningful support, not opportunistic upselling.
Customers experience helpful suggestions instead of annoying and irrelevant selling tactics. The banking platform seamlessly fits into their lives, providing meaningful, respectful support without feeling invasive. By placing customers in control of their communication settings, trust and loyalty grow. Contextual interactions become building blocks of a responsive, value-adding relationship rather than one-dimensional marketing.
Instead of feeling “sold to,” customers feel genuinely assisted. They control when and how they receive suggestions, ensuring that alerts and offers feel like welcome help rather than marketing “noise.”
Use Case Examples
- Next-Best Action: Contextual Banking uses customer, behavioral and journey signals to determine what assistance is useful at a particular moment. The appropriate next action may be guidance, a warning, a service, an offer—or no intervention at all.
- Geolocation-Based Tips: When a customer travels abroad, the app may highlight local currency exchange options or travel insurance add-ons.
- User-Defined Preferences: A privacy-conscious customer can limit push alerts to monthly summaries, while a more engaged user receives gentle, timely suggestions during everyday transactions.
5. Green Banking: Sustainable Finance Made Actionable
What Is Green Banking?
Green Banking integrates environmental considerations into financial products and digital experiences, helping customers make more informed sustainable financial choices. It can include energy-efficient financing, sustainable investments, environmental impact information and digital tools that make sustainability-related options easier to understand and act on.
Aligning Finance with Values
In an era of climate crisis and social upheaval, banks that ignore sustainability signal that they’re stuck in a moral vacuum. This alienation not only loses customers but erodes credibility.

Green Banking weaves ESG (Environmental, Social, Governance) considerations into everyday financial decisions. Sustainable products, transparent investment screenings and carbon accountability empower customers to align their finances with personal values. Your brand stands out as a beacon of purposeful, responsible leadership with a statement that profit isn’t the only bottom line you care about.
Green Banking integrates ethical and environmental values into the customer experience. From subtle nudges toward sustainable investment portfolios to transparent ESG frameworks guiding credit products, banks help customers align their financial decisions with personal ethics. Responsible product design, carbon-neutral initiatives and sustainability scorecards empower customers to measure the impact of their financial choices.
Behind the Green Banking Trend
As climate change and social justice issues top public discourse, people increasingly align spending and investing with their beliefs. They don’t just want a bank—they want a brand that supports their worldview.
- Shoppers check ethical sourcing. Investors watch ESG ratings. Ethical considerations now drive buying and investment decisions, including banking choices.
- Sustainability-linked loans, green bonds and ESG funds are reshaping financial portfolios, and brands that don’t adapt will appear to be out of touch.
- Blockchain-enabled traceability, robust reporting tools and AI-driven ESG analytics allow transparent measurement of environmental and social impact, making sustainability credible and measurable.
Impact on Your Financial Brand
Aligning with social and environmental values transforms your brand into a purpose-driven beacon. In a climate-aware era, this moral stance can become a key differentiator, attracting socially conscious customers who want their finances to reflect their values. Emphasizing sustainability is more than a marketing move; it’s a deeper promise that your brand is part of a better future—reinforcing loyalty, admiration and lasting brand love.
When banking aligns with personal values, the financial relationship transcends pure utility. Customers feel pride in their choices and see their bank as a champion of positive change. This value-centric alignment enhances emotional bonds, differentiates the brand and resonates deeply with socially conscious segments, driving loyalty and advocacy.
Use Case Examples
- ESG Investment Filters: Customers can explore funds that align with their social and environmental priorities, using transparent ESG ratings.
- Sustainable Lending: Banks encourage mortgages that support eco-friendly homes, offering favorable rates for energy-efficient improvements.
- Green Rewards: Customers earn eco-points or receive insights into the positive impact of their financial behaviors, such as reduced carbon footprints through digital statements.
6. Social Banking: Community, Peer Insight and Co-Creation
What Is Social Banking?
Social Banking introduces carefully governed forms of community participation, peer insight and customer co-creation into financial experiences. It can help customers learn from anonymized benchmarks, relevant communities and shared financial behaviors while keeping privacy, regulated advice and consequential financial decisions appropriately controlled.
Turning Customers into Communities
Social Banking uses carefully governed peer insight, anonymized benchmarking, community participation and customer co-creation to make financial experiences less isolated and more collaborative.
By daring to hand some control back to customers, Social Banking confronts the long-held belief that banks must stand aloof. Instead, it embraces vulnerability and acknowledges that fellow customers, not bankers, hold many of the answers. Of course, peer experience can provide context, but regulated financial advice should remain appropriately governed.

Social Banking transforms your financial brand from a solitary service provider into a community hub. Customers can learn from one other, share financial best practices and even co-develop new product features. Banks host forums, facilitate peer-to-peer knowledge exchanges and spotlight customer success stories. Crowdsourced feedback helps shape new functionalities, while mentorship circles connect seasoned savers with novice investors.
Behind the Social Banking Trend
In the age of social media and creator communities, customers are no longer passive consumers. They want a seat at the table, helping build products and experiences that benefit not only themselves, but everyone.
- Online communities and peer-to-peer advice platforms thrive in every sector. Customers increasingly trust user-generated content and peer recommendations.
- Crowdsourcing product feedback and involving customers in decision-making have become hallmarks of modern, transparent brands.
- Integrated community platforms, social features baked into apps and data analytics that identify community leaders and influencers make it easy to nurture a thriving financial ecosystem.
Impact on Your Financial Brand
When customers interact, advise one another and contribute feedback in brand-hosted environments, your brand becomes a community catalyst. This organic exchange of knowledge and support casts your brand as open, inclusive and forward-thinking. Customers aren’t just users—they’re valued voices shaping the brand’s future. As trust and camaraderie grow, your brand moves beyond transactional territory to become a social anchor point that customers feel proud to affiliate with.
By empowering customers to help each other and contribute ideas, banking relationships become dialogues instead of monologues. This collaborative environment builds trust, reduces isolation and provides practical, real-world insights. Customers feel valued and recognized, fostering long-term loyalty and community-driven brand affinity.
Use Case Examples
- Community Discussion Groups: Young professionals share budgeting hacks, while retirees discuss wealth preservation strategies, all moderated and supported by the bank.
- Insights About Similar Users: Banks can share common data for similar users to allow people and businesses to compare their financial situation with others. For example, save 50% more, following people in similar geographic, family and financial situations.
- Peer-to-Peer Learning Modules: Gamified learning experiences allow customers to teach each other, earning badges and recognition for their contributions.
7. Lifetime Banking: AI-Powered Financial Guidance Across Life
What Is Lifetime Banking?
Lifetime Banking organizes financial services around customers’ evolving goals and life stages rather than isolated product transactions. It connects everyday banking, saving, borrowing, investing, protection and financial planning into a relationship that can adapt as customers’ financial needs and priorities change over time.
Guidance for Every Life Stage
Lifetime Banking organizes financial services around evolving customer goals rather than independent product sales. Everyday banking, saving, borrowing, investing, protection and planning become parts of one relationship that adapts as financial needs change.
In a world that worships quarterly earnings, investing in a customer’s lifetime well-being is a radical act. Banks that refuse this holistic perspective remain trapped in a transactional mindset, blind to the deep loyalty that Bank-as-a-Product approach can generate.

Lifetime Banking replaces short-term, transactional thinking with long-term, holistic guidance. It focuses on guiding customers through all life milestones—new careers, home purchases, children’s education, retirement planning—always anticipating needs and offering transparent, ethical advice.
Advanced AI engines understand customers’ evolving goals. Customers receive ongoing, proactive advice tailored to life’s changing chapters, ensuring smooth transitions, informed decisions and a comprehensive suite of lifestyle-oriented financial services. Your brand becomes a steady presence that grows and adapts with the customer, cementing long-term loyalty.
Behind the Lifetime Banking Trend
In a world of one-off services and digital fly-by-night operations, a reliable financial partner who is ready to support you throughout your life is especially valuable. Brands that can provide true continuity and foresight in digital services will become indispensable.
- People seek holistic guidance in finance, not just point-in-time transactions. A bank that understands their evolving journey fosters stronger emotional bonds.
- Wealth management, financial planning and robo-advisory tools are migrating from the elite corners of finance to everyday digital banking, democratizing long-term guidance.
- AI-driven life-event prediction, secure data storage and integrated personal finance management systems enable long-horizon planning at scale.
Impact on Your Financial Brand
Positioning your brand as a steady companion throughout life’s journey infuses the relationship with depth and continuity. Customers perceive the brand as a guiding force that genuinely cares about their long-term success. This consistent, forward-looking support builds emotional resilience into the brand relationship, ensuring that your institution remains relevant, trusted and cherished over decades rather than drifting in and out of relevance.
By delivering continuous, context-aware and future-focused guidance supplemented with lifestyle-centric services, banks become more than service providers—they become holistic life partners. Customers appreciate the long-view approach that not only reduces financial complexity but also supports their personal interests, well-being and aspirations.
By maintaining a long-term perspective, banks transcend the transactional and become trusted allies. This deepens emotional loyalty and encourages strong, enduring relationships as customers journey through their financial and personal life stages.
Use Case Examples
- Goal-Based Planning: A 30-year-old customer receives guidance on saving for a home down payment, while a 55-year-old gets advice on optimizing investments for retirement income stability.
- Proactive Life Milestone Alerts: Approaching a major event—like a child’s college admission—the bank suggests savings adjustments, loan options or scholarships to explore.
- Lifestyle Services and Products: Beyond traditional financial offerings, banks curate a range of lifestyle-enhancing solutions. For example, a customer nearing retirement might gain access to preferred travel rewards, tailored insurance packages, partner discounts on home improvements or health and wellness benefits that adapt as their priorities evolve.
Megatrend: Invisible and Agentic Banking—From Manual Transactions to AI Execution
Invisible and Agentic Banking represent the convergence of many forces transforming financial services. As banking becomes more connected, contextual, personalized and automated, customers increasingly spend less time manually managing routine financial tasks while AI takes a more active role in helping them achieve financial goals.
Invisible Banking moves repetitive financial execution into the background. Agentic Banking goes further by introducing AI agents capable of interpreting customer goals, planning multi-step actions and executing them within clearly defined permissions and limits. Together, they can shift digital banking from a place where customers manually initiate every transaction toward an intelligent financial environment in which routine actions happen automatically while customers retain oversight of goals, rules, permissions, exceptions and consequential decisions.
This does not necessarily mean the disappearance of the banking app. Its role may instead evolve—from a transaction interface into a financial control center where customers understand what AI is doing, define what it is allowed to do, review outcomes and intervene when necessary.
What Is Invisible Banking?
Invisible Banking is a financial experience model in which routine banking actions increasingly happen in the background with minimal active effort from the customer. Payments, saving rules, fraud protection, financial monitoring and other repetitive tasks can be automated or embedded into everyday digital experiences, while customers retain visibility and control over important decisions, permissions and exceptions.
The objective is to reduce unnecessary financial administration rather than remove customer awareness. As more execution becomes invisible, the banking experience can focus increasingly on supervision, understanding, goal-setting and the moments where customers genuinely need to make a decision.
What Is Agentic Banking?
Agentic Banking uses AI agents that can interpret customer goals, plan multi-step financial actions and execute them within clearly defined permissions and limits. Unlike traditional automation, which follows predefined rules, agentic systems can respond to changing context, coordinate actions across multiple financial services and determine which steps are required to achieve an intended outcome.
For example, an AI agent could help a customer manage upcoming obligations, identify available surplus cash, adjust predefined saving rules and prepare a recommendation for how the remaining funds could be allocated—all within boundaries established by the customer.
As autonomy increases, transparency, authorization, explainability, safeguards and Systemic UX Governance become essential. The more consequential the financial action, the more explicit customer oversight should become.
From Invisible Automation to Agentic Finance
Invisible Banking is not simply another digital feature. It represents a broader shift in the relationship between customers and financial services.
For years, banking digitization focused on moving activities from branches to screens: checking balances, transferring money, paying bills and managing products through mobile and online banking. The next evolution reduces the need to initiate every routine action manually.
At the first level, automation executes predefined instructions.
At the second level, Invisible Banking embeds those actions into everyday financial life with minimal intervention.
At the third level, Agentic Banking can interpret goals, determine appropriate steps and coordinate multiple actions within customer-defined boundaries.
The progression can therefore be understood as:
Manual Banking → Automated Banking → Invisible Banking → Agentic Banking
But greater autonomy does not mean less control. The relationship changes from customers controlling every individual action to customers controlling the rules, goals and boundaries within which actions can occur.
Banking That Requires Less Attention—but More Trust
One of the core ambitions of Invisible Banking is to reduce unnecessary cognitive effort.
Routine financial administration—recurring payments, account monitoring, saving transfers or basic financial safeguards—should not require constant attention when customers have already defined what they want to happen.
Agentic Banking can extend this principle by helping customers coordinate more complex financial goals. Instead of simply triggering a predefined rule, an AI agent may evaluate several possible actions and determine which combination best supports the customer’s stated objective.
For example, rather than sending a generic reminder that an account balance is low, an agent could identify an upcoming payment, recognize available funds in another account, assess the customer's transfer rules and suggest—or, if explicitly permitted, execute—the appropriate transfer.
The experience becomes more effortless, but the intelligence behind it becomes more sophisticated.
This makes trust and control central UX requirements. Customers need to understand:
- what the system is doing;
- why an action was recommended or executed;
- which permissions the AI currently has;
- which financial limits apply;
- which actions always require approval;
- how to change or revoke those permissions;
- and what happens when the system is uncertain.
The future of invisible banking is therefore not financial activity that customers cannot see. It is financial complexity they no longer need to manage manually.
The Technology Behind Invisible and Agentic Banking
Invisible and Agentic Banking depend on several technological capabilities working together.
- AI and agentic systems can interpret goals, context and financial information to determine appropriate actions.
- Open APIs and connected ecosystems allow services to communicate and coordinate across banking and non-banking environments.
- Real-time data enables systems to respond to changes in balances, transactions, obligations and customer context.
- Automation executes routine processes without requiring repeated customer input.
- Digital identity and authentication help confirm when actions can happen seamlessly and when stronger verification is required.
- Modular banking architecture allows financial capabilities to operate across different channels and embedded environments.
Technology, however, is only the infrastructure. The customer value depends on how these capabilities are combined into an understandable, trusted and well-governed experience.
How the Seven Trends Converge Into Invisible and Agentic Banking
Invisible and Agentic Banking build on the seven experience trends rather than replacing them.
- From Customizable to Adaptive and Agentic: Customers first configure their preferred tools, information and rules. Over time, AI can adapt those environments and execute approved actions around changing needs while preserving customer-defined boundaries.
- From Connected to Embedded and Orchestrated: Connected channels evolve into financial ecosystems in which services can operate across banking, commerce and partner platforms. Agentic AI can coordinate actions across those environments rather than requiring customers to move between them manually.
- From Live to Intelligent Assistance: Conversational AI and human support evolve toward AI agents capable of helping customers resolve needs, prepare decisions and complete approved actions. Human expertise remains available for uncertainty, high-consequence decisions and situations requiring judgment.
- From Contextual to Proactive: Contextual Banking identifies what may be useful at a particular moment. Agentic Banking can take the next step by preparing or executing an appropriate action when the customer has explicitly authorized that level of autonomy.
- From Green to Values-Based Automation: Sustainability preferences can become explicit customer-defined criteria that AI considers when presenting or managing relevant financial options. Values should be declared and controllable rather than silently inferred.
- From Social to Collective Intelligence: Peer insight, anonymized benchmarks and ecosystem data can contribute additional context, while AI helps customers interpret that information without turning community behavior into uncontrolled financial advice.
- From Lifetime to Goal-Oriented Agentic Banking: Long-term financial guidance evolves from recommendations toward AI-assisted orchestration of saving, investing, borrowing and protection around customer-defined goals and changing circumstances.
Together, these shifts move digital banking from providing tools that customers operate toward creating financial systems customers supervise.
Impact on the Financial Brand
Invisible and Agentic Banking fundamentally change where brand experience occurs.
When customers interact less frequently with traditional transaction screens, brand differentiation cannot depend only on visible interfaces. It increasingly depends on how intelligently, transparently and responsibly the financial system behaves on the customer’s behalf.
This makes Digital Brand Identity especially important.
A bank positioned around empowerment should give customers clear control over AI permissions and decisions. A bank positioned around simplicity should make complex automation understandable. A premium financial brand may distinguish itself through sophisticated guidance and human escalation. A trust-led institution should make transparency and safeguards exceptionally visible.
In other words, Digital Brand Identity must extend from how the product looks to how autonomous financial systems behave.
Agentic Banking also raises the cost of inconsistency. A poorly worded recommendation is inconvenient; an incorrectly executed action can have financial consequences. As banks move from suggesting to acting, Systemic UX Governance, risk controls and customer authorization become increasingly important parts of the experience itself.
The institutions that succeed will not necessarily be those that automate the most. They will be those that establish the clearest relationship between autonomy and customer control.
Use Case Examples
For customers, Invisible and Agentic Banking can reduce routine financial administration while keeping important decisions understandable and controllable.
- Automated Financial Flows: Customers can define rules for incoming salary, recurring bills, saving and investment contributions. Routine execution then happens automatically, while significant deviations or exceptions remain visible.
- Agentic Cash-Flow Management: An AI agent can monitor upcoming obligations, expected income and available balances, then suggest or execute permitted transfers to reduce the risk of shortfalls while respecting customer-defined minimum balances and limits.
- Embedded Financial Services: Relevant services such as travel insurance, financing or payment options can appear directly within a purchase journey. The customer remains informed about terms and chooses whether to proceed.
- Proactive Financial Safeguards: AI can identify unusual transactions, potential overdrafts, duplicate payments or missed obligations and take predefined protective actions—or request customer approval when the consequence is significant.
- Goal-Based Saving Automation: A customer defines a goal and acceptable monthly contribution range. The system can adjust contributions within that range as income and spending fluctuate, while larger changes require confirmation.
- Agentic Financial Planning: Customers can define goals such as building an emergency fund, reducing debt or preparing for retirement. An AI agent can coordinate recommendations across saving, budgeting, borrowing and investments, while customers approve consequential changes.
- Embedded Payroll and Income Management: A freelancer can define rules for tax reserves, emergency savings and operating expenses. Variable income is then allocated automatically according to those instructions, with exceptions surfaced for review.
- Contextual Embedded Financing: When an unexpected expense occurs, relevant financing options can appear within the transaction context with transparent pricing, eligibility and repayment implications. AI can help compare alternatives but should not conceal the fact that credit is being used.
- Values-Based Investment Automation: Customers can explicitly define sustainability, risk and investment preferences. Automated investing can then operate within those boundaries instead of silently inferring personal values or reallocating investments without consent.
- Adaptive Life-Stage Guidance: When customers update goals or circumstances, the system can suggest adjustments to saving, protection or investment strategies. Agentic execution can automate approved routine changes while preserving explicit confirmation for consequential financial decisions.
The defining principle across these examples is simple: the more financial execution becomes invisible and autonomous, the more visible customer control needs to become.
Invisible Banking removes unnecessary effort. Agentic Banking adds intelligence and autonomy. Together, they can transform banking from a system customers constantly operate into one that increasingly works around their goals—without removing their authority over the financial decisions that matter.
The Future of Digital Banking Is Not More AI Features—It Is a Different Customer Relationship
Competition among financial brands has shifted from a fight over locations, fees, relations and service range to a fight over meanings, digital brand identities, customer experience and innovations.
As advanced technology becomes more accessible across the financial industry, functional differentiation becomes harder to sustain. AI capabilities, APIs, automation, personalization engines and digital infrastructure are increasingly available to many banks, which means features can converge quickly and competitors can replicate individual innovations faster than before.
In this environment, the experience layer becomes the real field of differentiation: how clearly the bank communicates, how coherently products connect, how intelligently services adapt to context and how confidently customers can act. AI accelerates this shift by making experiences more dynamic, personalized and proactive—but it also makes weak strategy and fragmented journeys visible faster.
These seven ultimate digital banking trends challenge financial brands to rethink their roles, leaving behind a narrow focus on products or transactional convenience. Instead, they help usher in a new era defined by shared values, flexible personalization, genuine community and lifelong guidance. Each trend underscores a reality: customers no longer accept banks as mere utilities—they demand meaningful, relevant and human-centric brand experiences.
Not every bank should pursue every trend. A wealth-focused institution may prioritize Lifetime, Live and Contextual Banking. A high-frequency retail bank may gain greater value from Customizable, Connected and Invisible Banking.
Strategic UX helps institutions determine which experience shifts support their customers, business model and Digital Brand Identity—and which trends would merely add complexity.
3 Strategic Shifts Behind Digital Banking Trends in 2026
1. AI Is Becoming Experience Infrastructure
AI increasingly powers personalization, assistance and automation across the entire customer relationship rather than existing as a single feature.
2. Feature Parity Is Moving Differentiation Toward Experience
As technologies become broadly accessible, Digital Brand Identity, customer understanding and experience quality become increasingly important competitive layers.
3. Greater Automation Requires Greater Customer Control
The more financial systems predict and act, the more important transparency, permissions, explainability and governance become.
Next-generation banking is no longer about offering mere conveniences—it’s about designing human-centered experiences that resonate emotionally and even influence customers’ behaviors at a positive level. This shift relies on delivering moments of delight, trust, and empowerment—events that trigger emotional reinforcement as customers interact with their finances.
Customizable modules, empathetic guidance, community-driven insights, ethically aligned investments and long-term mentorship all merge into a rich ecosystem of meaningful engagement. AI becomes the unseen conductor of these experiences—fine-tuning timing, tone, and relevance so that banking ceases to be a chore and emerges as a seamless extension of the customer’s lifestyle.
5 Actions for Banking Leaders in 2026
As experiences become more adaptive, AI-driven and distributed across ecosystems, consistency cannot depend on individual design teams. Systemic UX Governance provides the decision rights, experience principles, standards and measurement needed to keep hundreds of product decisions aligned with one customer experience strategy.
1. Identify Which Trends Support Your Strategy
Do not implement trends because competitors are doing so.
2. Define the Target Customer Experience
Specify how the institution should behave across products, channels and AI interactions.
3. Build the Enabling Capabilities
Data, APIs, modular architecture, AI and identity infrastructure often enable several trends simultaneously.
4. Protect Digital Brand Identity
Ensure increasingly personalized and AI-generated experiences remain recognizably part of one financial brand.
5. Govern Customer Outcomes, Not Feature Output
Measure adoption, effort, trust, conversion, retention, cost-to-serve and relationship value—not only releases.
So, is there still room for unique financial brands in a digital world dominated by standardization and commoditization? As we see, recent financial services trends say yes—unique experience isn’t just possible; it’s exactly what customers now demand.
Digital Brand Identity Matters More as Banking Becomes AI-Powered
When banks gain access to similar AI capabilities, functional differentiation can narrow quickly. Digital Brand Identity becomes the layer that translates common technology into a recognizable financial experience.
Customization should still feel like your bank. AI assistance should communicate like your bank. Contextual recommendations should reflect your customer philosophy. Embedded services should reinforce rather than dilute the brand promise. As digital experiences become more dynamic and personalized, Digital Brand Identity becomes more—not less—important.
Emotional design plays an important role across these trends. UXDA's Dopamine Banking approach uses progress, meaningful feedback and positive reinforcement to make financial interactions more motivating without turning banking into entertainment. Emotional value is one layer of the broader experience transformation—not a substitute for usability, trust or strategic relevance.
The decisive advantage therefore does not come from technology alone, but from the institutional system that turns technology into coherent customer value.
Strategic UX defines which customer and business outcomes matter. Bank-as-a-Product connects channels, products and services into one evolving relationship. Digital Brand Identity ensures that increasingly adaptive and AI-powered experiences remain distinctive and recognizably part of one financial brand. And Systemic UX Governance keeps hundreds of product, technology and operational decisions aligned over time.
Together, these capabilities determine whether new technology becomes another layer of complexity—or a clear, valuable and differentiated banking experience customers can understand, trust and prefer.
Digital Banking Trends 2026: Key Questions
What are the top digital banking trends in 2026?
The most important digital banking trends in 2026 include AI-powered personalization, Agentic Banking, Embedded Banking, Connected Banking, Contextual Banking, Invisible Banking, real-time financial services and increasingly adaptive customer experiences. From a customer experience perspective, these shifts can also be understood through Customizable, Connected, Live, Contextual, Green, Social and Lifetime Banking—experience models enabled by AI, APIs, automation, data and digital identity.
How is AI changing digital banking?
AI is changing digital banking by moving from isolated chatbots and recommendation engines toward a broader intelligence layer across the customer relationship. It can personalize interfaces, interpret financial context, provide conversational guidance, automate routine processes and increasingly coordinate multi-step actions. The strategic challenge is no longer simply whether a bank uses AI, but whether AI creates relevant, transparent and trusted customer value.
What is Agentic Banking?
Agentic Banking uses AI agents that can interpret customer goals, plan multi-step financial actions and execute them within clearly defined permissions and limits. Unlike traditional automation, which follows predefined rules, agentic systems can adapt to context and coordinate actions across financial services. As autonomy increases, customer authorization, transparency, safeguards and Systemic UX Governance become increasingly important.
How is personalization changing banking?
Banking personalization is evolving from static segmentation and targeted product offers toward real-time, contextual and adaptive experiences. AI can help tailor dashboards, guidance, recommendations and financial actions around individual goals, behavior and circumstances. The strongest personalization does not simply predict what product a customer might buy next—it identifies what action is genuinely useful at that moment, including when no intervention is needed.
What is Embedded Banking?
Embedded Banking integrates financial services directly into non-banking products, platforms and customer journeys. Payments, financing, insurance, savings or other banking capabilities can appear within commerce, travel, business software or digital ecosystems at the moment they are needed. The customer experiences the financial service as part of the wider activity rather than as a separate trip to the bank.
What is Contextual Banking?
Contextual Banking adapts financial guidance, services and interactions to the customer’s current situation, goals, behavior and journey. It uses relevant data and real-time signals to determine the most useful next action—such as guidance, a warning, a service, an offer or no intervention at all. Contextual Banking shifts personalization from “next-best product” toward next-best customer action.
What is the future of mobile banking apps?
Mobile banking apps are likely to remain an important financial control layer, but their role may change. As more transactions become automated, embedded or managed by AI agents, the app can evolve from a place where customers manually execute every action into a control center for goals, permissions, financial oversight, AI activity and exceptions.
Will AI replace banking apps?
AI is unlikely to make banking apps irrelevant. Instead, it can change what customers use them for. Routine execution may increasingly happen in the background through Invisible and Agentic Banking, while the app becomes more important for understanding financial activity, managing AI permissions, reviewing recommendations, approving consequential actions and controlling the wider banking relationship.
How can banks differentiate when features become similar?
As feature parity increases, differentiation shifts toward the experience layer. Banks can differentiate through Strategic UX, Digital Brand Identity, superior customer understanding, coherent cross-product experiences, emotional value and the way AI behaves on behalf of customers. Competitors may be able to copy individual features, but it is harder to replicate a distinctive experience system rooted in strategy, brand, culture and customer insight.
Which digital banking trends should banks prioritize?
Banks should not pursue every trend. Priorities should depend on the institution’s customer segments, business model, strategic positioning, Digital Brand Identity and organizational capabilities. A wealth-focused bank may prioritize Lifetime, Live and Contextual Banking, while a high-frequency retail bank may gain more value from Customizable, Connected, Invisible and Agentic Banking. Trends should inform strategy, not replace it.
How should banks measure the impact of digital transformation?
Banks should measure digital transformation through customer and business outcomes rather than feature output alone. Relevant metrics can include digital adoption, journey completion, conversion, customer effort, support demand, operational efficiency, trust, retention, cross-product engagement and long-term relationship value. The right measures depend on the problem being solved and should be defined before implementation rather than added after launch.
Get UXDA Research-Based White Paper "How to Win the Hearts of Digital Customers":
If you want to create next-gen financial products to receive an exceptional competitive advantage in the digital age, contact us! With the power of financial UX design, we can help you turn your business into a beloved financial brand with a strong emotional connection with your clients, resulting in success, demand, and long-term customer loyalty.
- E-mail us at info@theuxda.com
- Chat with us in Whatsapp
- Send a direct message to UXDA's CEO Alex Kreger on Linkedin